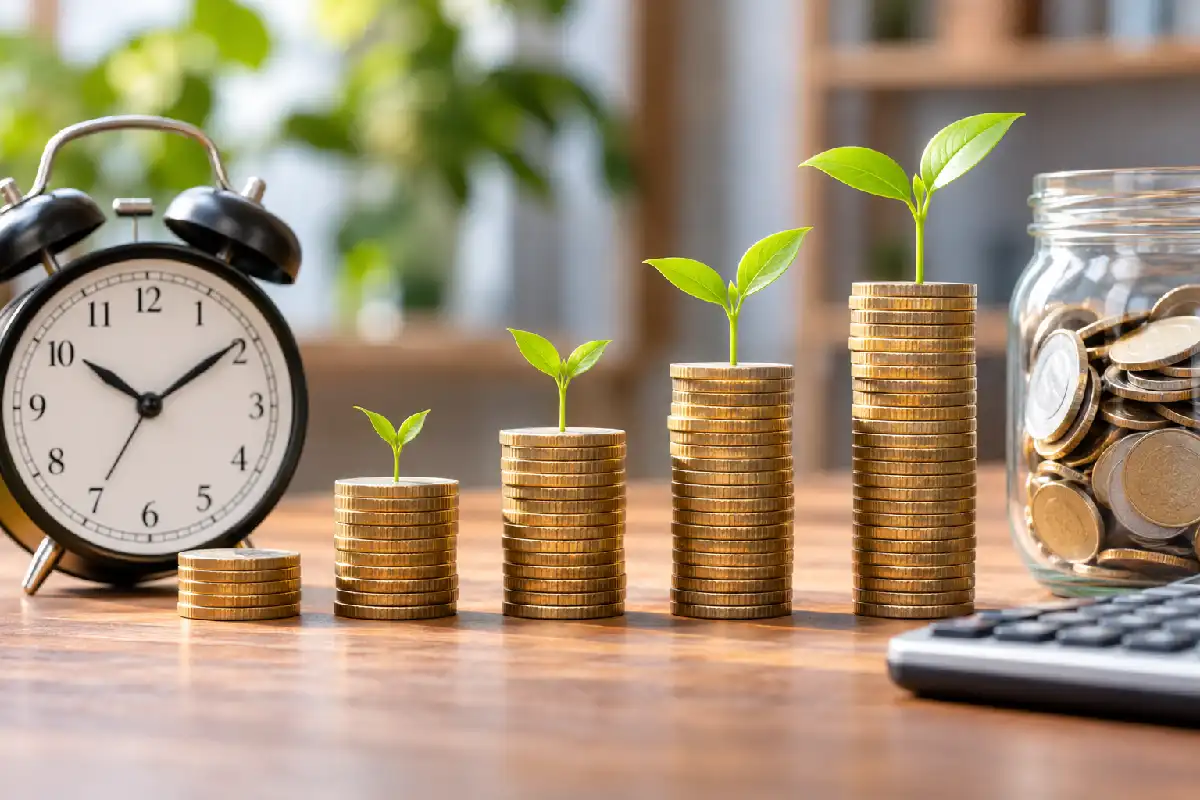
Every year you wait to start investing is a year you give away the power of compounding. When you delay investing by five years, the visible cost is simple: you invest for fewer years. The hidden cost is much bigger: your money gets fewer years to grow on its own.
In the early years, it may feel like “waiting a bit” will not matter. Your income is still rising, other priorities look urgent, and starting a SIP or long‑term investment plan can be easy to postpone. But compounding rewards time more than it rewards effort. The longer your equity or balanced investments stay invested, the more they can potentially grow.
Over a 20–30 year horizon, a five‑year delay can mean:
- A much smaller final corpus for the same monthly contribution.
- Or, you needing to invest a much higher amount every month just to catch up.
- The difference often runs into several lakh, and in long horizons may even approach a crore or more, depending on your actual returns.
For family goals such as your child’s education, a home down payment, or your retirement corpus, this “cost of delay” can directly affect how secure and independent your future feels.
Table of Contents
How Compounding Works in a Long-Term Investment Plan
Returns on Your Investment and Accumulated Returns
Compounding means you earn returns not only on your original principal, but also on the returns you have already earned. In simple interest, only your initial investment earns interest. In compound interest, last year’s growth also works for you.
In a long‑term SIP or investment plan, your money is invested in assets such as equity or debt funds. When those assets grow, the gains stay invested. Over time, this loop of “returns earning returns” becomes more powerful. The longer your investment horizon, the more years compounding has to work.
This is why starting early, even with a small amount, can be more impactful than starting late with a higher amount.
How Regular Contributions Build a Potential Corpus
Most Indian investors use a monthly SIP or systematic premium in an investment‑linked insurance plan. Each payment adds to your principal and gets its own compounding timeline.
Early instalments enjoy the maximum benefit because they stay invested for more years. The SIP contributions you make in the last few years before your goal have very little time to grow. When you delay your first five years of contributions, you are not just “skipping” those payments; you are losing the decades of compounding that those early amounts could have enjoyed.
Two investors can have the same income, the same return assumption, and the same final age goal. The one who starts a SIP at 30 instead of 35 can still end up with a significantly higher corpus simply because their money had more time in the market.
Compound Interest Formula and Its Inputs
The basic compound interest formula for a lump sum is:
A = P × (1 + r/n)^(n × t)
Where:
- P is the principal (amount you invest),
- r is the annual interest or return rate,
- n is the number of compounding periods per year,
- t is the number of years,
- A is the amount you get at the end.
A SIP or regular contribution uses a series of such calculations, one for each instalment. The key inputs that affect your final corpus are:
- How much you invest each month.
- How early you start.
- How long you stay invested.
- The return your investment actually earns over time.
You cannot control market returns, but you can control when you start and how consistently you invest.
Compare Starting Now With Starting Five Years Later
Keep the Monthly Contribution the Same
Imagine you invest a fixed amount every month into an equity‑oriented SIP or a market‑linked insurance plan. If you start now and invest for, say, 25 years, each instalment gets its own compounding journey.
If you wait for five years and invest the same monthly amount for only 20 years, the difference in your final corpus is not just five years’ worth of contributions. It is also the lost growth on all the money you could have invested in those first five years. That is the real cost of delay.
Keep Total Contributions the Same
Now imagine both investors put in the same total amount over time. The late starter must contribute much more every month to match the early starter’s corpus.
For example, if an early investor builds a target corpus by investing a modest monthly SIP for 25 years, a late investor with the same goal and the same assumed return over only 20 years may have to invest almost double every month to catch up. For many households, such a jump in monthly outgo is simply not practical.
Starting early allows you to work towards the same goals with a more comfortable contribution.
Read the Estimated Corpus Difference
Any SIP or compound interest calculator will show that the gap between starting now and waiting five years widens as:
- Your time horizon gets longer (for example, retirement at 60), and
- Your return assumption increases (for example, more equity exposure).
Even if both investors end up investing the same number of lakh over time, the one who started early typically ends up with a significantly larger final corpus. That is the compounding penalty of delaying investments.
Estimate the Cost of Delay With a Calculator
Enter Your Amount, Time Horizon, and Assumed Return
A SIP calculator can estimate how delaying your investments may affect your future corpus. Choose a calculator designed for regular contributions, rather than applying the lump-sum compound interest formula alone. Then enter your monthly SIP amount, contribution frequency, investment period, and assumed return. To see the impact of waiting, compare starting now with starting five years later while keeping the same goal date and monthly contribution.
- Enter your planned monthly SIP or annual premium.
- Select your investment horizon in years.
- Add a reasonable long-term return assumption based on your chosen asset allocation. Treat it as an estimate, not a guaranteed rate, because market-linked returns can vary. Also select how often you will contribute, such as monthly or annually.
You can also enter a lump‑sum principal if you plan a one‑time investment alongside your SIP.
Compare Contribution and Delay Scenarios
Next, run simple comparisons:
- Scenario 1: Start now, with your chosen monthly amount for your full time horizon.
- Scenario 2: Delay investing by five years, but keep the same monthly amount and end goal age.
- Scenario 3: Delay five years, but increase your monthly contribution until the calculator shows a similar maturity value to Scenario 1.
Looking at these scenarios side by side shows you:
- The potential cost of a five‑year delay in rupee terms.
- How much extra per month you might need to invest later to make up for waiting.
- Whether such higher contributions are realistic for your income and other commitments.
To build a sustainable SIP investment plan, start with a monthly amount that fits your budget after essential expenses. Keep an emergency buffer for unexpected costs so you can continue investing without disrupting your day-to-day finances. Review your plan as your income, responsibilities, and goals change. When your budget allows, increase your contribution gradually to stay on track towards future security.
Understand Estimates, Market Risk, and Inflation
Calculator results are illustrations, not guarantees. They usually:
- Assume a constant return rate, while actual market‑linked returns vary from year to year.
- Taxes, fund expenses, and product-specific charges can reduce the amount available at your goal date. Their impact varies by investment and product: mutual fund SIPs may involve fund expenses and applicable taxes, while investment-linked insurance plans may also have policy charges. These costs can lower your net returns, and inflation can reduce the future buying power of your corpus. Check the relevant product documents and tax rules when estimating your goal amount.
- Often ignore inflation, which reduces the future buying power of your corpus.
When you see a future value expressed in lakh or crore, remember:
- Market‑linked products carry risk; higher potential returns come with volatility.
- Past performance does not guarantee future results.
- Match your investment plans to each goal’s time horizon and your ability to tolerate losses. For a goal that is many years away, you may be able to include more equity, which has growth potential but can fluctuate. For a nearer-term goal, consider a larger share of lower-volatility assets to help limit the impact of market swings. Review your asset allocation regularly and consider shifting towards lower-volatility assets as the goal approaches.
For long‑term goals such as retirement, combining growth‑oriented investments with life cover can protect your family’s dreams even if something unexpected happens to you.
Questions About Compounding and Delayed Investing
How Does Compounding Affect a Five-Year Delay?
A five‑year delay shortens the period over which compounding can work. In the early years, your corpus is smaller, so the effect may not look dramatic. But towards the later years, when your accumulated amount is higher, each extra year of compounding can add a large rupee value.
By skipping the first five years, you lose not only those contributions but also all the growth they could have generated over the rest of your investment journey.
Can Increasing Contributions Help Address a Late Start?
Yes, increasing your contributions can partly offset a late start. A higher SIP or premium:
- Raises your principal faster.
- Gives more money a chance to compound.
However, there are limits. To catch up fully, you may have to invest far more each month than feels comfortable, especially if you are also managing home loans, education costs, or other family responsibilities. It is usually easier and less costly to start early with a modest amount and step up your contributions gradually as your income grows.
Are Calculator Returns Guaranteed?
No, SIP and compound interest calculator returns are not guaranteed, especially for market‑linked products such as equity funds or unit‑linked insurance plans. Calculators:
- Offer estimates based on assumed rates of return.
- Do not promise or guarantee any particular performance.
- May not include all costs, charges, or taxes that apply to actual products.
Treat them as planning tools to understand the impact of delay, not as promises of future income. Read product brochures carefully, understand the difference between guaranteed and market‑linked benefits, and, if needed, consult a financial advisor before deciding how to invest.
Starting early, investing regularly, and protecting your family with suitable life cover can together help you move towards a more confident and independent financial future.